
Business owners
Price health coverage for your team
- No spam
- No obligation
- You’ll work with one licensed agent from start to finish

- Google reviews: 4.8
- Real PeopleBased In Dallas, TX
How team quoting works
 Tell us about your companyYour business name, ZIP and how many people you want to cover.
 Add your teamA quick average age, a list of ages, or the employee list you already have.
 See one monthly totalEvery household priced on its own plan and added up, then talk it through with your agent.
Coverage for your team
One monthly total for your whole team
We price an individual plan for each employee household, with spouses and children optional, and add them up so you see one number. It isn’t a group health plan, so nobody is locked into a plan that doesn’t fit them.
Start my team quote Each household, its own planPriced individually, then totaled for your company
 No employer contribution requiredOffer coverage without committing to pay premiums
- List billing for 5 or moreOne monthly bill for the team
 Straight answersIf an ACA plan fits someone better, we’ll tell you
Is a Private PPO right for your business?
 A Private PPO plan may be a good fit if you are:
- Small teams
- Solo owners and partners
 Healthy, mixed-age teams
 Teams on the move
 Who this may not be for
- Owners whose income qualifies for a Marketplace subsidy (for their own coverage)
- Team members with serious ongoing health conditions (an individual ACA plan may fit them better)
- Businesses that need an ACA-compliant group plan
- Employers with 50 or more full-time employees, who face the ACA’s employer coverage rules
Plan types
How plans compare
Most of the difference people feel day to day comes down to the network.
| Feature | Private PPO | Typical HMO | Typical EPO |
|---|---|---|---|
| Use any doctor or hospital | ✓Yes | –In-network only | –In-network only |
| See a specialist without a referral | ✓Yes | –Referral needed | ✓Usually |
| Benefits for out-of-network care | ✓Yes | –Emergencies only | –Emergencies only |
| Benefits anywhere in the U.S. | ✓Yes | –Local network | –Plan’s network |
ACA Marketplace plans are a better fit if you earn less than about $64k annually as an individual (qualify for subsidies) or are experiencing ongoing health conditions. We’ll compare both with you and help you find the best fit.
Before you get a quote
A few things worth deciding first, so the numbers fit your business.
- Who to coverHow many people, and whether to include their families
- What the business paysHow much of the premium, if any, the company covers
 Where your team livesWhether your people are spread across states
- What matters mostPrice, doctor choice or simplicity for your team
Patient advocacy
We’ll help you navigate the healthcare system
A U.S. based advocacy team handles the paperwork on your policy.
 Pre-price careWe shop the procedure before you go
 File claimsWe submit and track every claim
 Negotiate billsIf a bill looks wrong, we push back
- Find doctorsTell us what you need and we’ll find it in-network
Patient Advocacy is a voluntary membership and not an insurance product. Bill negotiation results aren’t guaranteed.
How patient advocacy worksMeet the team in your corner
Licensed agents and advocates in Dallas who know your name and answer when you call.
Ben JonesFounder 
Nick KlusmeyerSales Manager 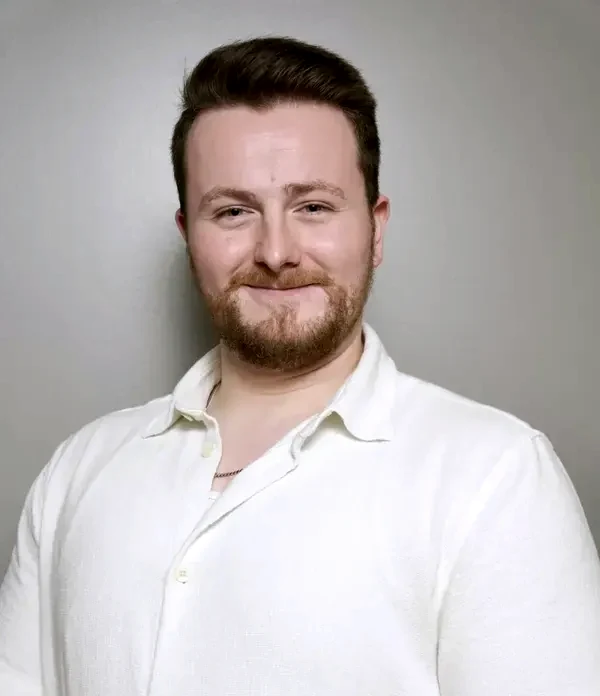
James RileyPatient Advocacy Manager 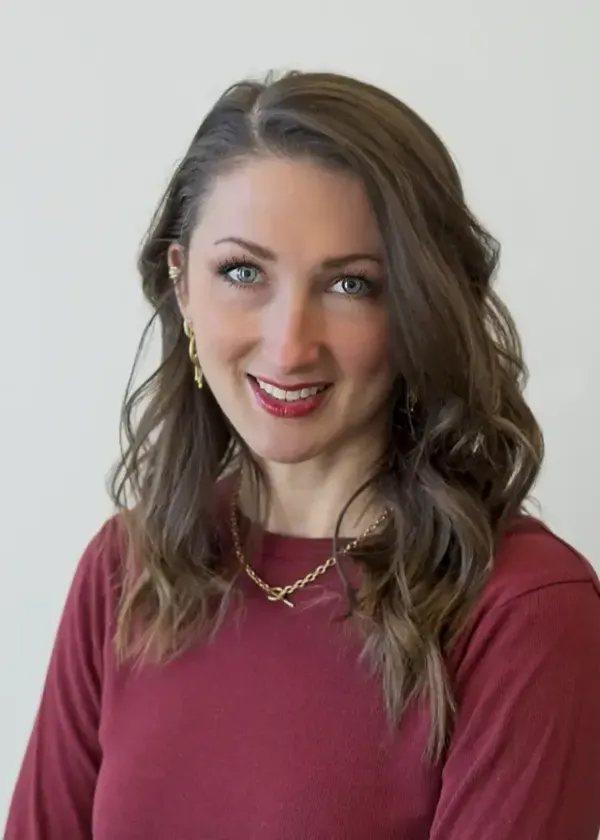
Samantha McHoneChief Marketing Officer
Coverage area
Enroll in your state, use it nationwide
If you live in a highlighted state, you can get a plan. Once you’re covered, the nationwide PPO network travels with you.
- Plans available to residents
- Nationwide PPO network
Perfect for:
- Visiting friends
- Vacations
 College
- Travel for work
What clients say
4.864 Google reviewsI am self employed and the marketplace plans are outrageously expensive. Noah helped me find private insurance for a very affordable monthly rate. I would highly recommend working with him.
Michelle A.Google review Pierce was so helpful and easy to work with. He explained things well and was easily accessible. He answered all of my questions and was very knowledgeable. Highly recommend!
Alissa B.Google review Mo was alot of help very knowledgeable about the plans and help every step of the way thank you
Nathan B.Google review Noah was great! He help me through the whole process and even work after hours to get my application going.
Martin R.Google review
Read on GoogleI'm thankful a close friend recommended Pierce. Working with him was amazing. He did a great job explaining how this insurance company and coverage worked, pricing, options, and the endless questions I had. What could have been a very stressful situation was made into a smooth process by Pierce. I can't thank him enough for being good at his job! If you're shopping for health insurance please give American Allly a call and ask for Pierce.
K R.Google review Very informative
Dave J.Google review
Questions from business owners
Is this a group health plan?
No. Each employee household gets its own individual plan, priced on the same rates as our individual and family quotes, and we add them up so you see one monthly total for your team. It isn’t a group health plan or employer-sponsored coverage. The rules on a business paying employees’ premiums vary, and your agent will walk you through the options.
Does the business have to pay part of the premium?
No. There’s no employer contribution required. You can offer the plans without paying premiums, or decide how much the business covers, and your agent will explain how each option works.
Can employees include their spouse or children?
Yes. Spouses and children are optional for every employee. Each household is priced for whoever is in it (employee only, employee and spouse, employee and children, or the whole family) and totaled for your company.
Can I send you my employee list?
Yes. Upload the list you already have, a payroll export, a carrier census or any spreadsheet with one row per person, or use our template. If you’d rather not, a headcount and ages are enough for a first quote. No names are needed.
Is this ACA major medical insurance?
No. The private plans are underwritten by Philadelphia American Life Insurance Company and are fixed indemnity plans, not ACA major medical coverage. They pay set benefit amounts for covered services, and there is no out-of-pocket maximum. If a Marketplace plan is a better option for someone on your team, we’ll tell you.
What if an employee has a pre-existing condition?
Private plans are medically underwritten and have a 12-month pre-existing condition limitation: anything a person was diagnosed with, treated for or took medication for in the 12 months before coverage starts isn’t covered for their first 12 months. Because each household has its own policy, a team member with a serious ongoing condition can choose an individual ACA Marketplace plan while the rest of the team uses a private plan.
How many employees can I quote?
From one to 1,000. Small teams are where this tends to fit best, and your agent will tell you if a different approach suits your business better.
Which states do you cover?
Our office is in Dallas, and our plans are available in 31 states: Alabama, Arizona, Arkansas, Delaware, Florida, Georgia, Illinois, Indiana, Iowa, Kentucky, Louisiana, Maine, Maryland, Michigan, Mississippi, Missouri, Nebraska, Nevada, North Carolina, Ohio, Oklahoma, Pennsylvania, South Carolina, South Dakota, Tennessee, Texas, Utah, Virginia, West Virginia, Wisconsin and Wyoming. If your team is spread across states, we’ll confirm what’s available where each person lives.