If you earn more than about $64,000 as an individual, or $132,000 for a family of four, and nobody in your household is managing a chronic condition, the 2026 marketplace will treat you very differently than it treats most people shopping it. This open enrollment is not a routine renewal.
Three things changed this year:
- At least nine insurance carriers are leaving the ACA marketplace, including one that sold plans in 11 states.
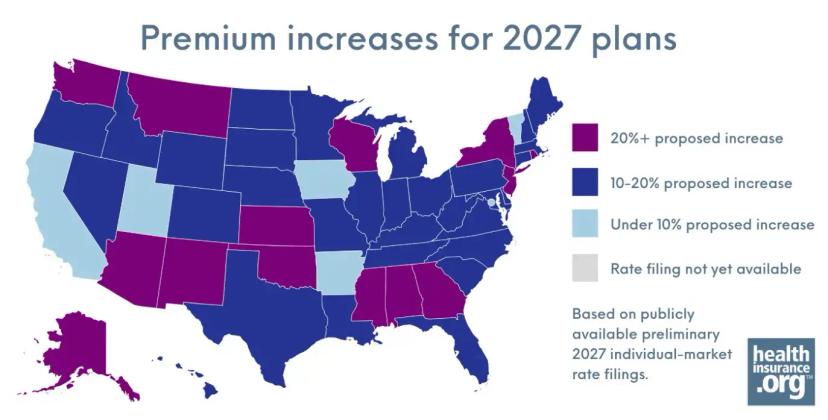
- Insurers filed for another double-digit premium increase, the second year running.
- The subsidy cliff is back in full force, so above a certain income the help to lower your premium does not shrink. It disappears.
Start with the dates. In most states you can buy 2027 coverage from November 1, 2026 through January 15, 2027, and December 15, 2026 is the cutoff for coverage starting January 1.
A few states run a different open enrollment calendar:
- Virginia closes January 29, 2027, two weeks after the federal window (Virginia’s Insurance Marketplace).
- Nevada gives you until December 31 for coverage starting January 1, not December 15 (Nevada Health Link).
- Georgia had not published its 2027 dates at the time of writing, so check Georgia Access directly.
What Changed for Open Enrollment 2026-2027:
1. Your Carrier May Not Be There
Cigna is leaving the ACA exchanges entirely, in all 11 states where it sold plans: Arizona, Colorado, Florida, Georgia, Illinois, Indiana, Mississippi, North Carolina, Tennessee, Texas and Virginia. That affects about 355,000 marketplace members, according to Cigna’s own first-quarter filing. Ten of those states are ones we serve.
Cigna is not alone. Medica is leaving Iowa, Kansas and Oklahoma, CareSource is leaving Indiana, Ohio and West Virginia, and Illinois has confirmed that Cigna and Molina plans will not be available on its marketplace from January 1. Counts differ by date, with KFF listing nine carriers and later tallies running higher.
What Happens If Your Plan Is Discontinued
The marketplace does not leave you uncovered. It suggests “an alternative plan from a different issuer selected by the Marketplace,” in the words of the CMS guidance, and states may build their own matching rules.
That is a plan somebody else picked for you, possibly with a different network, drug list and deductible. Losing a discontinued plan also counts as losing qualifying coverage, which opens a special enrollment period running 60 days before the loss and 60 days after. The before half is what prevents a gap, and it is the half almost everyone misses.
2. Premiums Rose Again
Insurers proposed a median increase of 15% for 2027 across 276 insurers in all 50 states and DC, according to the Peterson-KFF Health System Tracker. Those are proposed rates rather than approved ones, so your renewal may land elsewhere. Last year’s finalized median was 20%.
“If these early indications of median premium increases for 2027 hold, typical premiums for insurers participating in the ACA Marketplaces will have jumped by more than one-third over a two-year period” (Peterson-KFF).
About 10 points of it is ordinary medical inflation: hospital costs, physician visits, prescription drugs including GLP-1s, and labor. That is higher than the 8% typical of recent years, and it is most of the answer. Another 4 points comes from who left the market, because when healthier people drop coverage the remaining pool costs more to insure.
3. The Subsidy Cliff Is Back
The enhanced premium tax credits that ran from 2021 through 2025 expired on December 31, 2025, and they were what removed the income ceiling on subsidies. Without them the old rule returns: above 400% of the Federal Poverty Level (FPL), the credit is not reduced. It is zero.
The House passed a three-year extension in January 2026 and the Senate has not acted on it. Proposals are still moving, but insurers filed 2027 rates on the assumption that nothing passes.
Who Actually Pays the 2027 Increase:
Not everyone, and that is not spin. Most enrollees still receive credits that absorb part of the increase before it reaches them, and 87% of them got one in 2026.
Where the Subsidy Cutoff Sits in 2027
| Household Size | 400% of FPL (subsidy cutoff) |
| Individual | about $64,000 |
| Family of 2 | about $87,000 |
| Family of 4 | $132,000 |
Earn a dollar over your household’s line and the credit does not taper: it disappears.
For a healthy middle-income household, that single dollar is the difference between a subsidized premium and the full sticker price.
What That Looks Like for One Person
Peterson-KFF followed one example through: a 40-year-old in Indianapolis earning $65,000, on a silver plan. With enhanced credits in 2025 the premium was $316 a month. In 2026 it was $477.
For 2027, if regulators approve the filed rates, it reaches $546. That is 41% more over two years, same person, same plan.
What the Marketplace Was Built to Do
This is not an accident or a failure. Marketplace plans have to accept everyone at the same price, whatever their health history. Insurers cannot turn anyone down or charge more for being sick, and every plan carries an out-of-pocket maximum and a drug list.
For someone managing a serious condition, or taking a medication that costs thousands a month, that is the difference between having coverage and having none. It is the entire point of the design and it works.
It also means your premium reflects the average cost of that whole pool rather than your own health. If you are healthy and your credits are gone, nothing stands between you and the full increase.
So the answer depends on which of those two people you are. If you qualify for meaningful subsidies, or someone in your household needs guaranteed coverage, the marketplace is where you belong, and we will say so on the phone too. If you are above the line and paying full price, it is worth seeing what else exists. You can learn more about how our plans work here!
What to Do Before Open Enrollment Closes:
Before you buy from anyone, including us, check them out: here is how to verify any health insurance company yourself. If you work for yourself, review health insurance options for self-employed and 1099 workers before renewing on autopilot.
1. Open the Letter From Your Insurer
If your carrier is leaving, it had to tell you. That notice documents your special enrollment period, and acting before your coverage ends is what keeps January clean.
2. Estimate Your 2027 Income, Not Last Year’s
Subsidy eligibility runs off your modified adjusted gross income (your adjusted gross income plus a few add-backs). Near that 400% line, a few thousand dollars decides whether you get a credit at all, so the estimate matters most when your income varies.
3. Shop Instead of Auto-Renewing
Proposed 2027 increases run from a 1% decrease to a 54% rise depending on the insurer, so last year’s cheapest plan is frequently not this year’s. Your children may also qualify for the Children’s Health Insurance Program on its own state income limits even when you do not.
The Real Costs of Coverage Through the Marketplace
Subsidies reduce premiums, but they do not solve deeper affordability problems. The 2026 plan year showed exactly how that plays out, and this open enrollment builds on top of it.
Gaps in Coverage Leave Families Exposed
Even with ACA protections, households still fall through the cracks. For anyone who loses job-based insurance mid-year, COBRA is often the only bridge, and it is an expensive one.
- COBRA Premiums: In 2025, employer family coverage averaged $26,993 per year, and COBRA only allows families to keep that plan and pay the full monthly premium themselves, without the employer contribution that had been covering most of it.
- Uninsured Risks: A three-day hospital stay costs $30,000 on average.
Why Subsidies Don’t Always Equal Savings
A credit lowers your premium. It does not eliminate your costs:
- High Deductibles: To absorb the 2026 premium jump, people bought down. Bronze enrollment rose from 30% to 40% of sign-ups while silver fell to a record-low 43%, and the average marketplace deductible climbed 37% in a single year, from $2,759 to $3,786 per person (KFF). That is the steepest rise since the marketplaces opened in 2014. The average bronze deductible now sits at $7,476. A 35-year-old in Dallas earning $65,000 on a Blue Cross Blue Shield plan carries a $7,500 deductible before most coverage begins.
- Narrow networks (HMOs and EPOs) keep premiums down by excluding hospitals and specialists, and by charging you everything if you go outside the network.
- Claim Denials: HealthCare.gov insurers denied 19% of in-network claims in 2024, and the rate ran from 3% at one insurer to 36% at another (KFF). Which company you pick matters as much as which plan.
In practice, “affordable coverage” can mean premiums you can pay and benefits you cannot use.
Affordable Alternatives Available Year-Round
Where Private PPO Health Insurance Plans Fit:
American Ally offers private PPO health insurance plans for people who are healthy, pay full price, and want something other than a marketplace renewal. They are primary coverage rather than a supplement, with nationwide PPO network access and full medical coverage in case something terrible happens.
For a healthy household paying an unsubsidized marketplace premium, these plans commonly run 40% to 50% less. Results vary by age, location, household and underwriting, and the plans are medically underwritten, so not everyone qualifies.
Key features include:
- $0 copays
- $0 outpatient deductible
- No coinsurance on outpatient care.
- Nationwide PPO network access.
A deductible applies only once a hospital stay runs 24 consecutive hours or longer, so same-day surgery and observation stays will not trigger one. When a charge runs above the plan’s amount, the difference is yours. The network’s negotiated rate usually covers it, and our patient advocacy team reviews the remainder, along with procedure pre-pricing, provider lookups and claims help.
Our Plans Are Not Ideal For:
- Anyone earning under roughly $64,000 as a single person, where marketplace subsidies make an ACA plan the better answer.
- Anybody managing a chronic condition or taking multiple ongoing prescriptions.
These plans are fully underwritten, so not everyone qualifies.
"I was paying over $1,299/month through my TRS plan just to keep my family insured. Even with a raise, it felt impossible to keep up. The deductible was more than my emergency fund.
I spoke with a licensed agent who showed me how I could stay on my TRS plan for about $19/month and move my husband and kids to a more affordable private plan.
That one change saved us over $650/month: more than $7,000 a year back in our pocket."Margaret* Saved Over $7,000/year!
(*Name and identifying details changed for privacy.)
Discover the #1 Strategy That Helps teachers Save Thousands On Their Health Insurance
How American Ally Helps Families Save
Understanding the types of coverage available is only part of the equation. For many families, the real challenge is navigating those choices and finding a plan that not only fits their budget but also works when they need care. This is where American Ally steps in.
We believe that Americans deserve affordable healthcare, and our team is dedicated to making that possible every day. We do this in two key ways:
Lowering monthly costs by connecting people with plans that are significantly less expensive than Marketplace or COBRA options.
Providing advocacy services that reduce bills and bring clarity to a system that often feels overwhelming.
Real People. Real Health Insurance Savings.
Travel Nurse (illustration based on a real case): She had been paying $302 per month for a US Health plan but switched to American Ally for just $192 per month. Not only did she save over $100 monthly, but she also gained access to a nationwide PPO network—crucial for a nurse traveling between states.
Retired Couple: After retirement, they were shocked when COBRA premiums came in at $1,700+ per month. They moved to an American Ally plan for just $745 per month, freeing up more than $11,000 annually to use for living expenses instead of insurance.
Self-Employed & Uninsured: Anita had gone uninsured for more than three years because traditional plans were too costly. American Ally helped her secure a PPO plan for $265 per month, finally putting affordable and usable coverage within reach.
These are not isolated stories. Every day, our team helps individuals, families, freelancers, retirees, and small business owners find solutions that put hundreds back in their pockets.
Advocacy services: pre-pricing and bill negotiation
Affordability doesn’t end when the premium is paid. For many Americans, the real sticker shock comes after care is delivered, when the medical bill arrives.
- The same lab test can cost several times more at a hospital than at an independent clinic a few miles away.
- Medical bills frequently contain errors, and a single coding mistake can add thousands to what you owe.
That’s why American Ally provides:
- Procedure pre-pricing: so you know upfront what a visit, lab, or surgery should cost.
- Post-bill negotiation: to challenge inflated or incorrect charges and reduce medical debt risks.
In short: American Ally does more than sell insurance. We partner with families to make sure coverage works in real life, not just on paper.
Open Enrollment 2026 Is the Year Doing Nothing Costs You…
The real answer to what changed this open enrollment is not on the calendar. If your insurer is one of the nine or more leaving the ACA marketplace, the plan you have now ends in January whether you open the envelope or not.
Insurers filed for another 15% increase on top of last year’s 20%, and if your income is above roughly $64,000 for a single person, the premium tax credit does not shrink. It disappears.
For too many households, that means paying more than ever for coverage they already struggle to use.
But families are not without options. American Ally private PPO plans provide year-round enrollment, $0 copays, no outpatient deductible, and nationwide PPO network access. With advocacy services like pre-pricing and bill negotiation, these plans are built so your benefits work in practice and not just on paper.
This is the year to actually open the envelope. If your carrier left and you let the renewal happen to you, the exchange hands you a plan somebody else picked, with a network and a drug list you never agreed to.
At stake are not just numbers on a renewal notice, but real families deciding whether they can afford to see a doctor, fill a prescription, or stay out of debt. With American Ally, you don’t have to face those choices alone.
Americans deserve affordable healthcare. And with American Ally, you have a healthcare ally for every step of the journey.
FAQs on Open Enrollment and Affordable Coverage
When Is Open Enrollment for 2026-2027?
In most states it runs November 1, 2026 through January 15, 2027, with December 15 the cutoff for coverage beginning January 1. Virginia runs through January 29, 2027, and Nevada allows until December 31 for January 1 coverage. Georgia had not published its dates at the time of writing.
Which insurance companies are leaving the marketplace in 2027?
Cigna is exiting the ACA exchanges in all 11 states where it sold them, affecting about 355,000 members. Medica is leaving Iowa, Kansas and Oklahoma, and CareSource is leaving Indiana, Ohio and West Virginia. Several others announced individual state exits. Every state still keeps competing insurers for 2027.
What happens if my health insurance company leaves the marketplace?
Your insurer must notify you, and the marketplace will suggest an alternative plan from a different insurer that it selects. That plan may carry a different network, drug list and deductible, so compare rather than accepting it by default. A discontinued plan counts as a loss of qualifying coverage, opening a special enrollment period that begins 60 days before the loss and runs 60 days after.
Will I still qualify for a subsidy in 2026-2027?
It depends on your modified adjusted gross income and household size. Most enrollees still receive credits. Above 400 percent of the poverty level, roughly $64,000 for a single person and $132,000 for a family of four, the credit is zero rather than reduced.
How much are marketplace premiums going up in 2026-2027?
Insurers proposed a median increase of 15 percent nationally, following a 20 percent median finalized increase for 2026. Individual proposals run from a 1 percent decrease to a 54 percent rise, so your own renewal matters more than the national median. These are proposed rates and may change in review.
What If I Miss the Open Enrollment Deadline?
You generally cannot buy a marketplace plan until the next window opens. Two things can still help. A qualifying life event opens a special enrollment period, and private PPO plans like ours enroll year-round without one, which is why people who miss January 15 often end up looking at them.
What Is a Special Enrollment Period and How Do I Qualify?
It is a short window that opens after a specific life event rather than on a calendar. Qualifying events include losing job-based coverage, moving, marriage, divorce, a birth or adoption, and having your plan discontinued. You have to document the event, and most windows run 60 days.
Are marketplace plans the only option during open enrollment?
No. The marketplace is the right answer for anyone receiving a meaningful subsidy or managing a condition that needs guaranteed coverage. For healthy households above the subsidy cutoff paying full price, private PPO plans are a real alternative worth comparing against the renewal notice.
Are Private Health Insurance Plans ACA Compliant?
Most private PPO-style plans, including ours, are not ACA compliant. They sit outside the ACA framework and do not include protections like an out-of-pocket maximum, carrying benefit maximums instead. They are also medically underwritten, so not everyone qualifies. For a healthy household paying full price, the tradeoff is often worth running the numbers on.
Do I have to re-enroll, or will my plan auto-renew?
Most plans auto-renew, which sounds convenient and often costs money. Carriers reprice every year, and if yours has left the market the exchange moves you to a plan you did not choose. Log in, update your income, and compare before December 15.
Who should consider private alternatives?
-
Generally, people who are healthy and paying the full unsubsidized premium:
- Self-employed workers and 1099 contractors.
- Small business owners.
- Early retirees who are not yet on Medicare.
- Teacher families carrying expensive dependent coverage.
- Anyone earning past the subsidy cutoff.